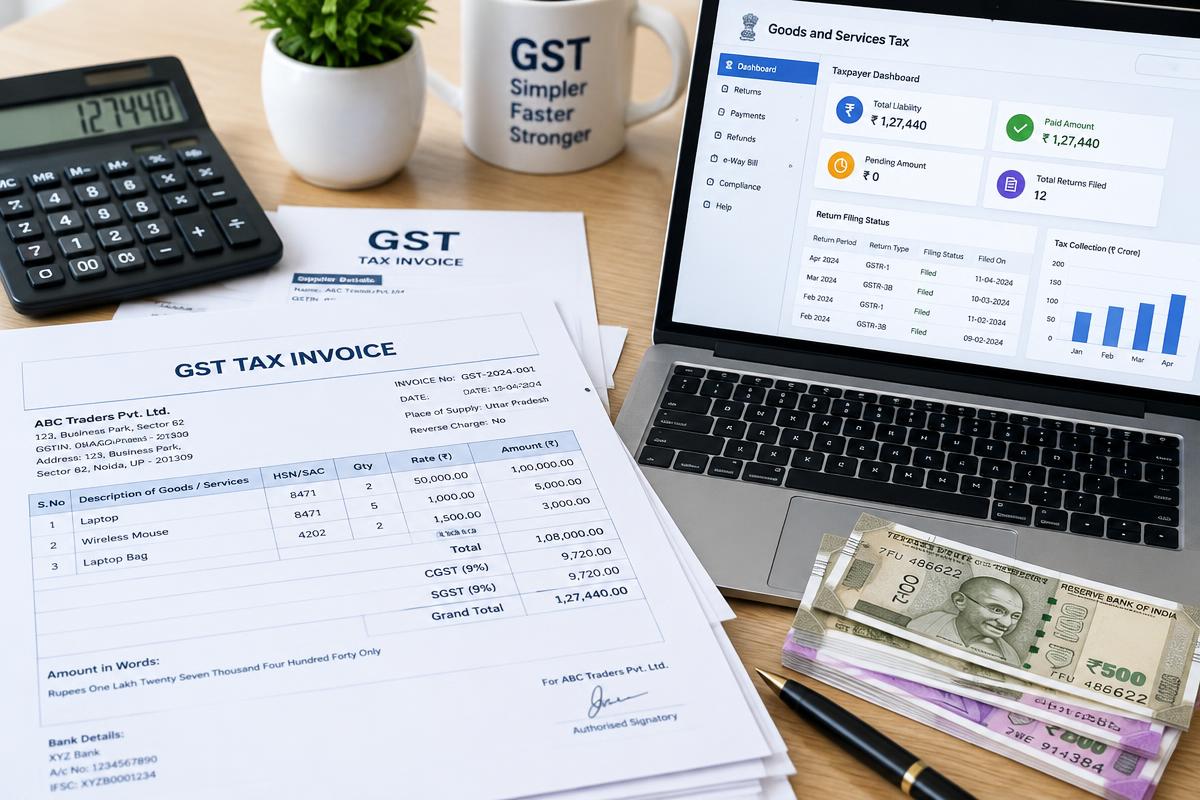
The illustrative scenario
A business paying contractors and employees should reconcile each payment stream instead of pooling deductions.
This is a planning illustration, not a client story or a promised result. Your transaction facts, entity and applicable rules can produce a different recommendation.
Identify what needs deciding
TDS compliance connects the underlying payment, deduction, deposit and deductee reporting.
Incorrect PAN or a mismatched challan can leave the recipient without the expected tax credit.
Write the question in business terms and separate what you know from assumptions. The adviser should explain which missing facts could materially change the proposed approach.
Gather evidence for the decision
Prepare TAN details, deductee PAN records, payment classifications and challan evidence.
Build a dated record of the facts and explain any inconsistent records. Keep originals and identify the source of each estimate; forecasts and actual financial results should not be presented as the same thing.
Turn the assessment into an action plan
Reconcile the deduction ledger to payments and challans before preparing the relevant statement.
Specify regular returns, correction statements, certificates and default-resolution support separately.
For each action, agree its owner, dependency and completion evidence. Obtain approval before a material decision is implemented and plan for possible requests for additional records.
Check the result and continuing responsibilities
Keep validated statements, challan mapping, certificates and a correction tracker.
How are deduction classifications and unmatched challans reviewed before filing?
Review what remains outside the assignment, including future compliance and recordkeeping. Request advice tailored to the actual facts rather than using this illustration as an instruction to file or transact.
How to use this resource