Start with the decision, not the product
Choose return treatment from the full income profile and applicable tax year, not salary alone.
This service is offered to salaried people, professionals and businesses. That audience description is not a legal eligibility test. Identify your actual objective, such as a suitable business structure, reliable reporting, a specific registration or a response to a notice.
The facts your adviser needs
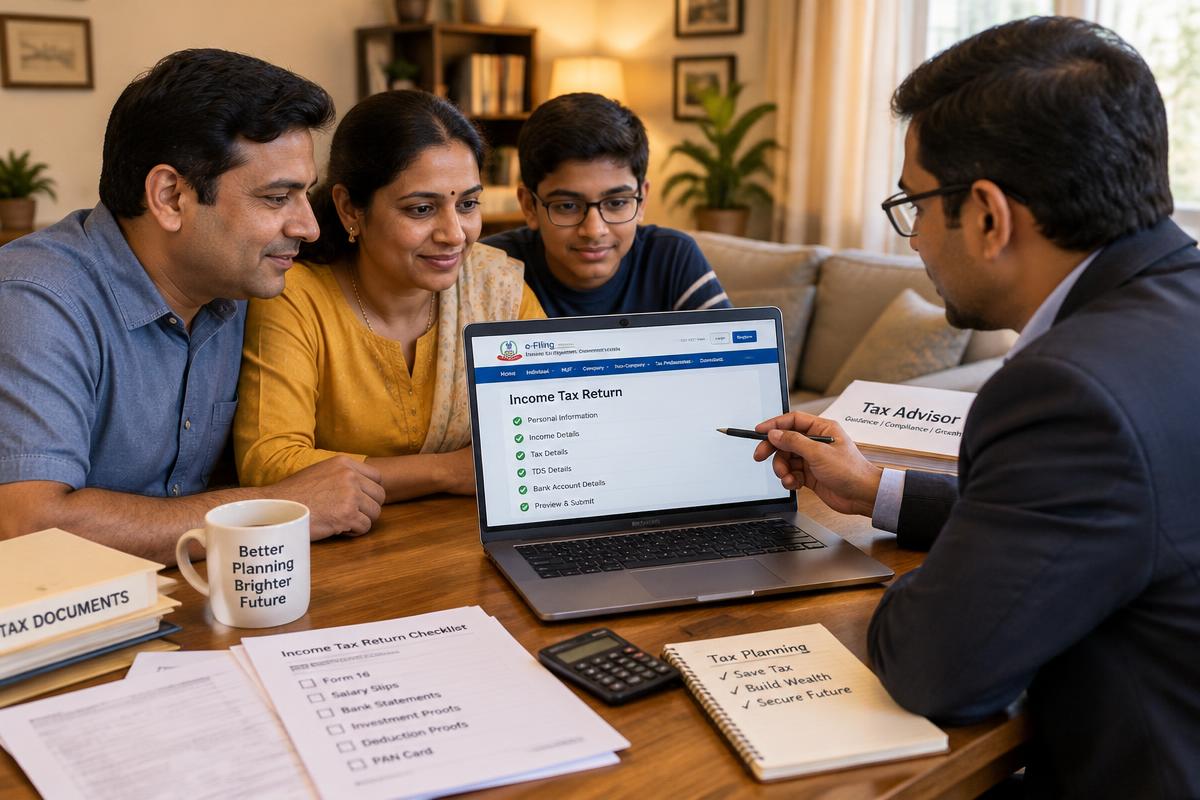
Collect salary and tax-credit records, bank interest, investment and capital-gain statements and other income evidence.
Explain your entity, activities, locations, relevant period and any planned changes. Also disclose existing applications, filings or advisers so duplicated work and conflicting instructions can be avoided.
Ask about alternatives and trade-offs
Ask whether a narrower engagement, a different structure or better internal records would meet the same objective. Compare ongoing obligations as well as the first task. If a requirement is statutory, ask the adviser to identify the applicable official rule and relevant exceptions.
Omitted interest, securities transactions or incomplete verification can undermine an otherwise filed return.
Make the readiness assessment concrete
Reconcile reported income and credits, compare applicable options and complete filing and verification.
Separate items you can resolve internally from those needing professional judgement or external approval. Record the dependencies and consider whether your team has enough capacity to maintain the resulting process.
Choose a next step you can verify
Will the final computation and mismatches be explained before I authorise submission?
Clarify whether capital gains, business schedules, foreign assets and follow-up queries are included.
Request a written recommendation that explains assumptions and the proposed scope. Where current eligibility or regulatory interpretation is uncertain, obtain case-specific advice before spending money or acting.
How to use this resource