Define the starting point and the outcome
Choose return treatment from the full income profile and applicable tax year, not salary alone.
Tell the adviser whether this is a new engagement, a transfer from another provider or a correction of earlier work. Identify open questions and the decision-maker who can approve assumptions and provide missing evidence.
The service workflow
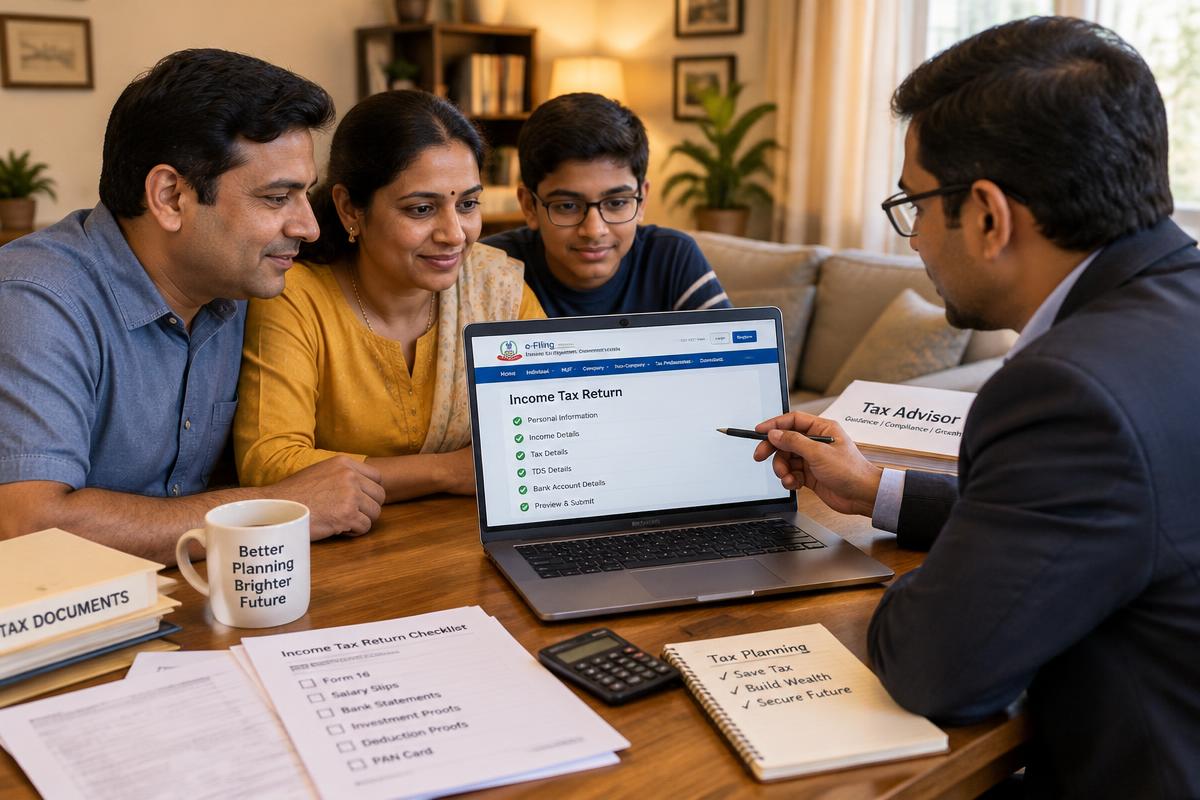
Reconcile reported income and credits, compare applicable options and complete filing and verification.
The steps below describe the existing service workflow. Confirm their applicability and current portal requirements before acting; the order and supporting evidence can change with the entity or case.
Step by step
- 1
Document review
- 2
Tax computation & planning
- 3
Choose right ITR form
- 4
Filing & e-verification
- 5
Refund tracking
Where your approval is needed
Approve key facts and calculations before a filing or report is finalised. Ask for a readable explanation of assumptions, unresolved differences and any choices with continuing consequences. For assurance work, management preparation and independent professional judgement remain distinct.
Will the final computation and mismatches be explained before I authorise submission?
How to manage delays and queries
Omitted interest, securities transactions or incomplete verification can undermine an otherwise filed return.
A useful status update names the outstanding item, its owner and the next action. Missing records, portal queries and third-party review can affect completion. Avoid treating an indicative service timeline as a guaranteed regulator decision.
What to retain when the work is complete
Retain computation, return acknowledgement, verification evidence and the supporting documents.
Confirm future responsibilities and record-retention arrangements in writing. Keep a copy of the final deliverables and know who controls access. If work continues monthly, agree the next reporting or compliance cycle before closing the current one.
How to use this resource